

You can read a PDF version of this article here.
Tiendas 3B (TBBB) reported Q3 earnings on Monday and if you read my previous earnings articles on the company, you’d probably guess what I am about to say: more business as usual, but in a great way!
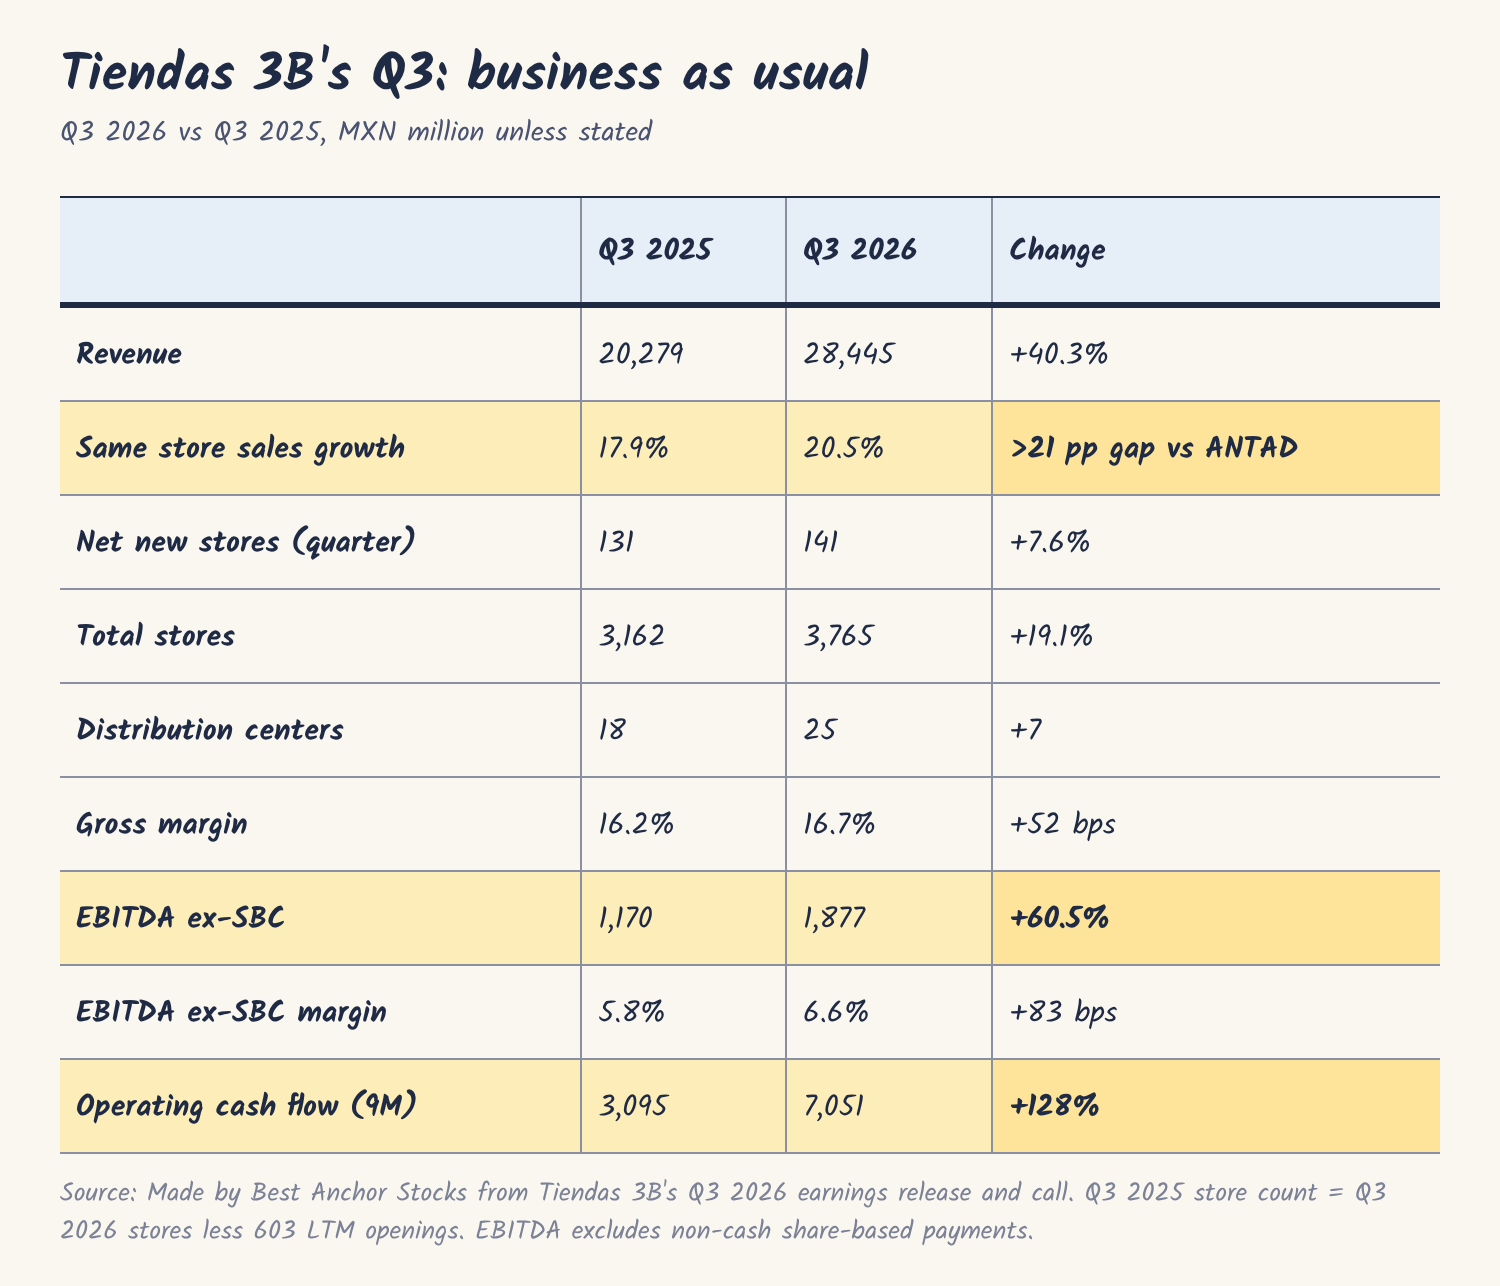
Revenue grew 40% on a base that is now above $1.5 billion USD, same store sales grew 20.5% against a comp of 17.9%, and EBITDA excluding SBC grew a whopping 60%. So, not only is revenue accelerating, but margins are also expanding alongside revenue growth.
I’ve long thought that owning “boring” businesses that just execute while receiving virtually no weekly news (because they tend to be out of the spotlight) is an underrated competitive advantage. Not only do you typically tend to get these businesses at a decent multiple from time to time, but they also take away a lot of the mental stress involved in other investments. I tend to think about these as “noise-cancelling” investments.
What I liked the most about this quarter wasn’t any single number but rather how boring the call was (again, in a good way). When an analyst asked about Q4 (next quarter), Anthony Hatoum’s (CEO) answer was pretty much the summary of the whole report:
“So net-net, everything is pointing in the right direction, and in the fourth quarter, just expect business as normal for us.”
Anthony Hatoum, CEO, Q3 2026 earnings call
Business as normal definitely sounds boring in a world of bottlenecks and AI trades, but at Tiendas 3B it actually means high 30s-low 40% growth, continued market share gains and improved margins and cash generation. I’ll take that kind of boring!
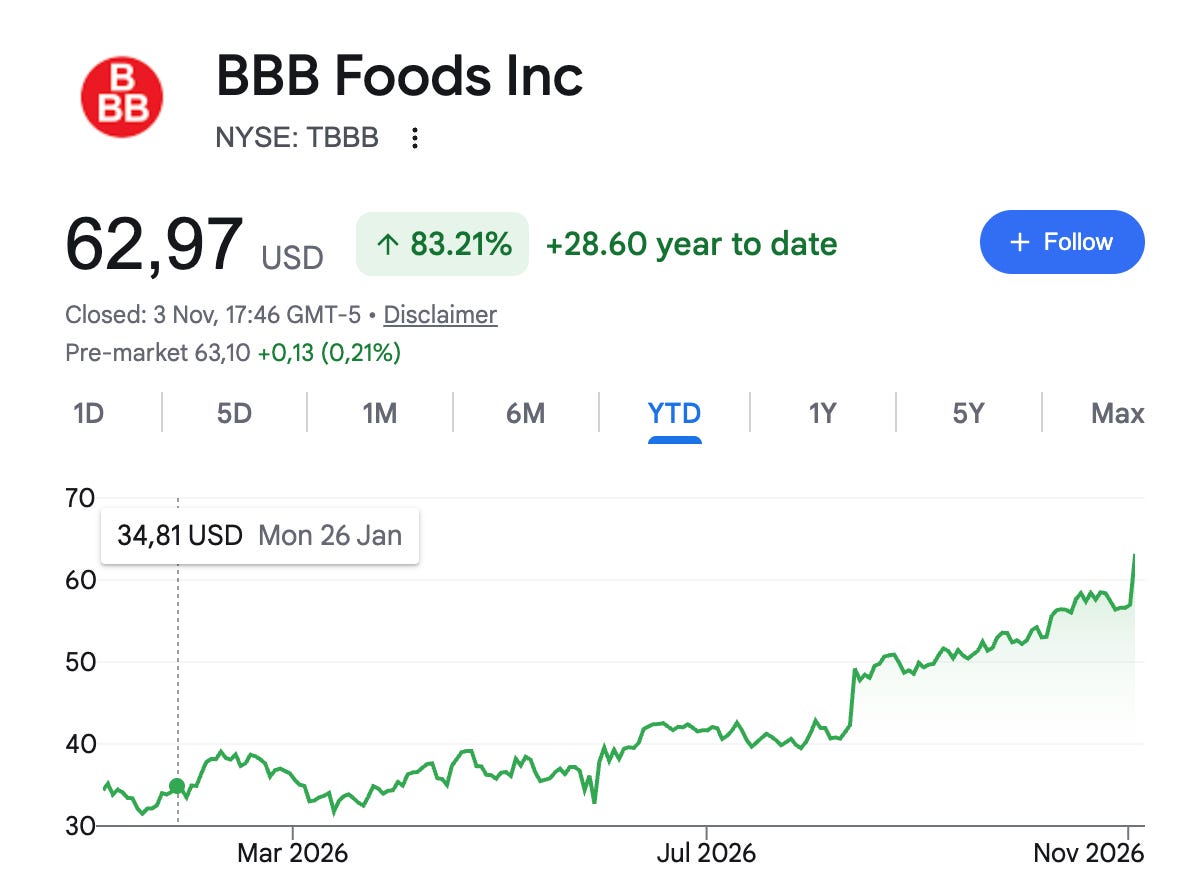
The shares evidently reacted positively to the news and now sit at ATHs (all time highs) and up a whopping 81% since I published my report in January this year:
(By the way, I decided to make my in-depth report free after the 75% run, so you can read that here.)
Here’s the quarter at a glance:
Tiendas 3B’s growth algorithm (like that of any retailer) has two engines:
Store openings
Same store sales (aka SSS).
One could argue that store growth has somewhat disappointed (maybe that “it has not been a highlight“ is a better way of putting it) whereas SSS growth has surprised even the most optimistic. This mix in the growth algorithm matters for profitability as SSS growth carries higher operating leverage.
The company opened 141 net new stores in Q3 to reach 3,765 stores. This takes LTM store openings to 603 which is a 19.1% store count growth (bot bad). It’s true that YTD openings stand at 419 and it’ll take a 191 store-opening quarter to reach the midpoint of the store openings guide (610) for the year, but management made it clear that they still adhere to the guide:
“No, we’re still well within guidance, and you’re absolutely right. The fourth quarter tends to be a little bit heavier on store openings, and our pipeline looks very healthy at this stage. So, no change in guidance.”
Anthony Hatoum, CEO
Performance vs guidance is an interesting topic. As an investor, you’d ideally want to own a management team that underpromises and overdelivers, and Tiendas 3B management is a good example of this dynamic. Store openings is the only one of the three guided metrics that isn’t running ahead of guidance.
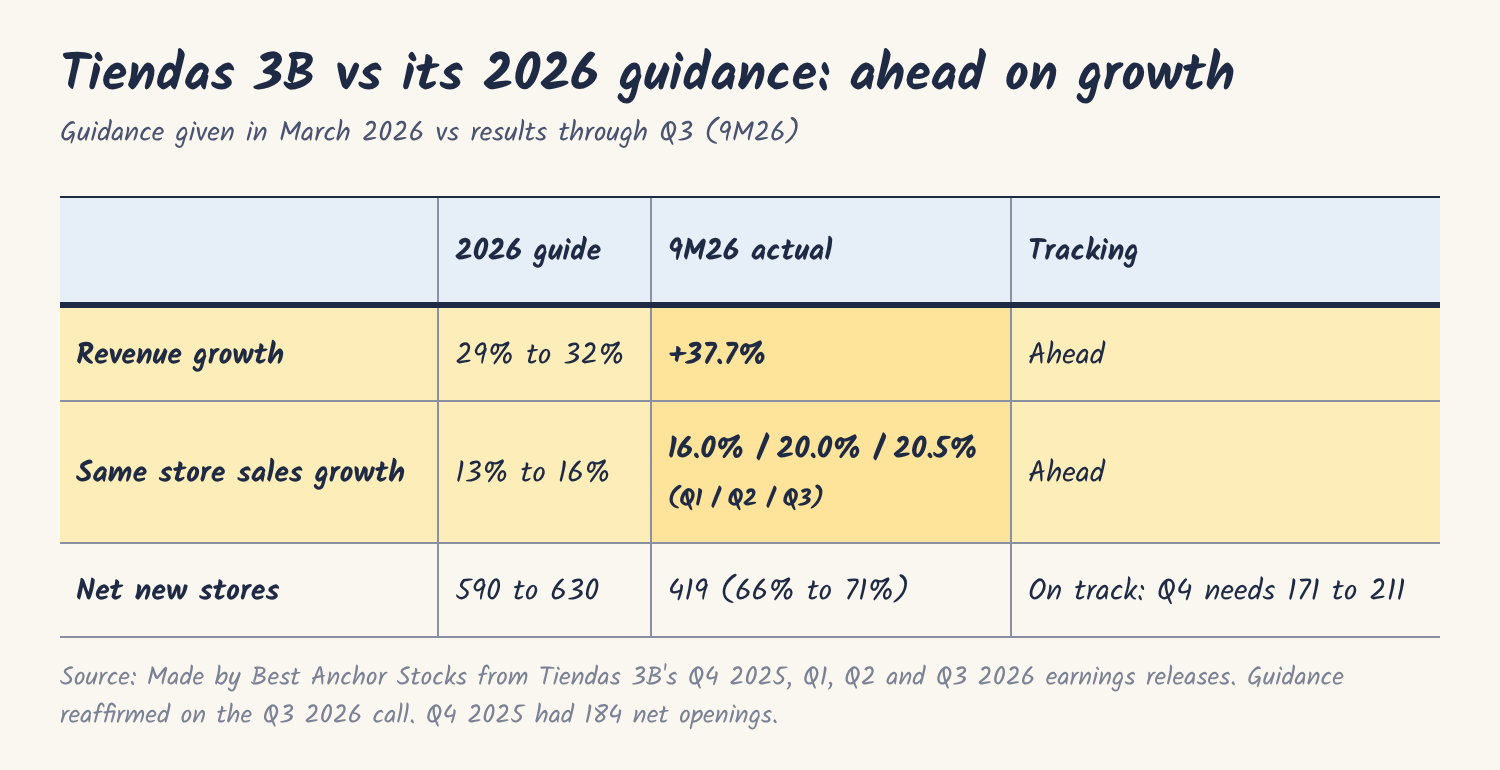
Back in March, management guided for 29-32% revenue growth, 13-16% SSS growth and 590-630 net new stores for 2026. Nine months in, revenue is up 37.7% and SSS have come in at 16.0%, 20.0% and 20.5% in each quarter. Not only has management outperformed their guide...they’ve blown past it!
For context...Tiendas 3B would only need Q4 revenue to grow around 17.5% to hit the top of the revenue guide, but with Q3 running at 40% and management claiming BAU (business as usual) in Q4, it’s highly likely that the company will come closer to 40% growth than to the guided 32%:
Despite this outperformance, management continues looking ahead. TBBB opened 4 new distribution centers in the quarter to reach 25 and management confirmed that each DC still serves roughly the same number of stores (my average is close to 160). This should help us understand the potential runway with existing DCs, and it’s pretty simple math. 25*160 is equivalent to 4,000 stores. With Tiendas 3B having 3,765 stores, that means that there’s still runway to open stores with the existing DC base (which one would think would be a pretty profitable endeavor!).
The highlight was once again SSS growth. SSS grew 20.5% against a tough comp of 17.9% in Q3 2025 (wow). This comes after 20% in Q2 (also on an 18% comp), which is hard to believe for a business with 3,765 stores that, let’s not forget, sells primarily grocery! How can they do this? Winning A LOT of share, which brings us to this absolutely incredible data point:
“During the quarter, we maintained a gap of more than 21 percentage points versus ANTAD while keeping our internal inflation very low.”
Anthony Hatoum, CEO
I read this a couple of times (I always do). ANTAD (what could be considered Tiendas 3B’s “industry”) was pretty much flat, while Tiendas 3B delivered 20% growth. What makes this even more impressive is that inflation is close to zero at Tiendas 3B due to its business model and increased private label penetration (which tends to be 30% cheaper). This is a headwind unlikely to be true for ANTAD as a whole.
With the above sales numbers you evidently get positive “surprises” in margins. Gross margin expanded 52 bps to 16.7%, sales expenses fell 36 bps to 9.8% of revenue, and admin expenses excluding SBC fell 6 bps to 2.6%. All of this resulted in EBITDA excluding SBC growing 60.5% to MXN 1.9 billion, a 6.6% margin (+83 bps YoY and up from 6.1% in Q2). Note that in my model I had a 7%-8% adjusted EBITDA margin as a steady state in 10 years and a 4.8% Adjusted EBITDA margin this year! (I’ll update my model later).
The reality is that with SSS growing at 20%, margins are likely to go bananas because every incremental peso of sales in an existing store comes with very little incremental cost. Total revenue growth will do what it needs to do, but the mix of its growth sources matters for the bottom line (and we should be aware of this to avoid surprises in the future).
This good profitability and fast growth combo is a significant tailwind for cash flows. In my in-depth report I tried to lay out the beauty of this business model:
“Despite profitability currently not being optimized, the beauty of the model lies in cash conversion: Tiendas 3B is already generating positive free cash flow despite being in a hyper-growth phase. This means that the model is self funding already and that Tiendas 3B will have significant cash to deploy (or return to shareholders) as it grows.”
“Thanks to scale and the hard discount business model, Tiendas 3B manages to turn inventory three times before having to pay suppliers. This ultimately means that suppliers are the ones financing the store growth.”
Bueno, Bonito, Barato (?), Best Anchor Stocks, January 2026
In the report I also shared an interesting case study using BIM (the Turkish hard discounter), which is ultimately the model that Tiendas 3B is executing in Mexico (the numbers have evidently varied a bit):
“According to my calculations, Tiendas 3B will generate around $8 billion in Free Cash Flow over the coming decade. For context, the current market cap is under $4 billion. This sounds unbelievable, but BIM generated 3x its 2016 market cap in Free Cash Flow over the following decade. Evidently, that money has not stayed still in the balance sheet and BIM has returned it to shareholders through dividends and buybacks, being additive to stock price returns.“
Bueno, Bonito, Barato (?), Best Anchor Stocks, January 2026
Operating cash flow for the first nine months reached MXN 7.1 billion, a 128% increase YoY (MXN 2.8 billion in Q3 alone). Adjusted negative working capital reached MXN 10.8 billion (vs 7.8 billion in 2025), around 10.9% of LTM revenue. We are already starting to see the above play out for Tiendas 3B. The company ended the quarter with MXN 3.1 billion in cash plus $237 million in USD short-term deposits, which is somewhere around 4% of the total market cap on a fully diluted basis. And this is happening while management continues to aggressively fund the buildout (working capital benefits will moderate once growth slows down).
Cash flows are not free of risks, though. Mexico’s new tax reform (approved by Congress on November 3rd and effective from January 2027) caps the deductions that profitable companies with more than MXN 50 million in income can take. The result is that they pay a minimum tax of roughly 1% of taxable income, with the disallowed deductions carried forward for up to 20 years. For Tiendas 3B, this ultimately means paying more cash taxes today and recovering them later. This is why management deems the impact to be “temporary” on cash flows although they are still working on the numbers:
“With the information that we have today, this is a law that would mainly affect temporarily cash flows. As of today, we do not expect any changes for our plans for next year.”
Eduardo Pizzuto, CFO
Other interesting tidbits
If I had to sum up the call in three words, those would be “business as usual.” Needless to say, for a company growing 40% with an improving value proposition, BAU is exactly what you want to hear! Let’s go over some pretty relevant points for the thesis.
First, newer stores keep getting better. This is one of the most important points for the thesis because it means incremental returns are going up. Anthony Hatoum mentioned it in his closing remarks:
“Our newer store vintages are performing better than our previous vintages. They start with higher initial sales, and their sales grow faster. This momentum continues into our fourth quarter.”
Anthony Hatoum, CEO
Secondly, the source of SSS growth also shows a healthy business:
“So, two-thirds is coming from volume, which is the number of tickets and price per ticket, and the balance is price. And within price, the vast majority comes from mix, not from inflation.”
Eduardo Pizzuto, CFO
In other words, customers are simply buying more stuff at Tiendas 3B, and when they pay a higher price it’s because they are trading up to higher-priced products, not because TBBB is raising prices. Price and volume both add up to growth, but I believe the latter is a considerably healthier source of growth (you can ask FICO why).
Thirdly, Tiendas 3B remains far from being an efficient operator despite current profitability improvements. Anthony Hatoum reminded analysts that margins will go up and down from quarter to quarter, but the main driver is scale and that “as we continue to scale, everything improves, including rebates.“ This scale benefit also transfers to transportation, where management argued that they have “barely scratched the surface“ and that we’ll see “a lot more happening in 2027 on that front.”
Fourth, discipline remains intact despite the fast growth. The SKU count “remains very conservative at around 900 products,” and every new product still forces the question of which one to drop (also a reason why stores are becoming more profitable over time). Despite the fast growth, this is a management team that thinks in returns and does not suffer from “empire-building” (at least thus far).
And last but not least, Yema. Tiendas 3B acquired Yema in 2023 to enter private-label organic food. The brand is sold in some Tiendas 3B stores, runs its own independent stores, and is a more premium concept that reminds me of what BIM did with FILE in Turkey (i.e., we know that both concepts can coexist).
This TBBB concept has only four stores, but management said it’s “hitting a niche of the market that nobody seems to have been looking at.” It’s way too early to model anything here but seems like good optionality nonetheless!
My updated model
With the strong rise in the shares as of late and the significant outperformance that TBBB has displayed...it was time to update the model. The key question I want to answer here is whether TBBB remains a good deal after the run...and the answer might surprise you.